Build a Financial Cushion Even on a Tight Budget
Reading time: 5 minutes
Last month my washing machine broke down. The repair: $340. Three years ago that would have put me in real trouble. Today it doesn't, because I managed to build a financial cushion even though my budget was anything but generous back then. That's exactly what this article is about: how to make it work even with little room to maneuver.
I've worked as an employee in Chicago for years, no top salary, lots of fixed costs. Still, over three years I built up a buffer of more than $9,000. Not by chance, but through a few clear decisions that I'll show you here.
Why you should build a financial cushion, even on a small budget
A financial cushion is not a luxury for high earners. It matters most precisely when your budget is tight, because otherwise unplanned expenses knock you off course immediately. According to a survey by the Swiss National Bank, in 2023 a significant share of Swiss households lacked sufficient liquid reserves for unexpected expenses (SNB, Financial Stability Report). That shows the problem doesn't only affect people with low incomes.
If you don't have a safety buffer, the next car repair or dentist bill quickly lands you on a credit card or a small loan. That's exactly what I want to prevent with this article. I've already described in detail how much of a reserve makes sense in my article on building an emergency fund.
The difference between saving and building reserves
Saving sounds like sacrifice, like vacations that never happen. Building reserves is something different: it's insurance against everyday life. You pay yourself a premium so that life doesn't catch you off guard.
Building a financial cushion on a small income: my approach
When my take-home pay was around $4,200, I didn't have $500 left at the end of the month. I still made it work, because I didn't treat saving as whatever was left over, but as a fixed item like rent.
The trick was an automatic transfer of $80, which went to a separate account the day after payday. Not much, but untouchable. Within 14 months, that added up to more than $1,100, without my having to actively think about it.
Automatic saving works better than manual saving because it takes the decision out of the moment. You don't have to talk yourself into it every month; the money is simply already somewhere else before you can spend it.
Small amounts, big impact
In parallel I kept a household budget and noticed how much was lost through small amounts alone, for example through forgotten subscriptions. If you want to know how heavily such items weigh on the budget, you'll find it in my post on subscription traps and hidden costs.
Concrete steps to create a money cushion
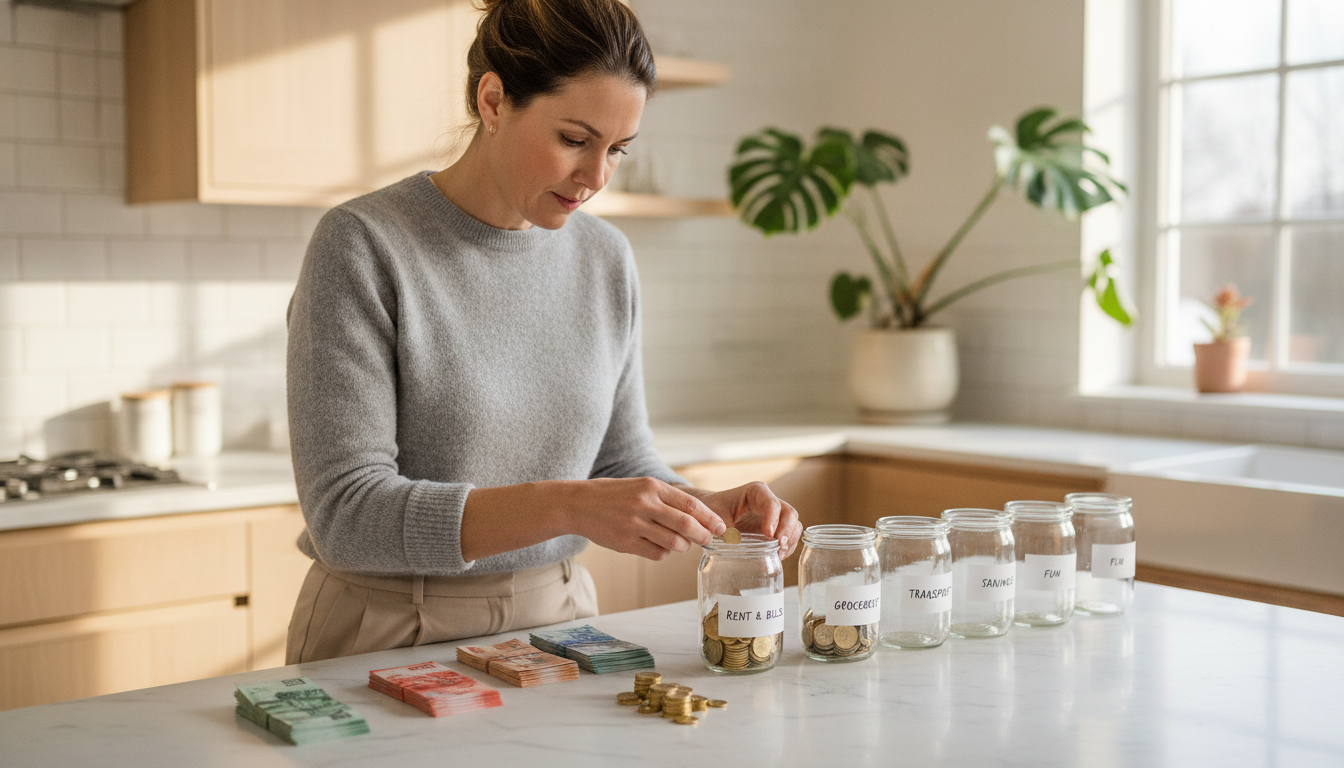
Building a financial cushion doesn't succeed through good intentions, but through a system. Here are the steps that worked for me:
- Open a separate savings account that isn't linked to your everyday debit card
- Set up an automatic transfer, right on the day after payday, not at the end of the month
- Keep the starting amount small; $50 to $100 is perfectly enough at first
- Send 50 percent of every unexpected windfall, such as refunds or gifts, into the cushion
- Every three months, raise the amount by $10 to $20 as soon as your budget allows
This system needs no spreadsheets and no complicated planning. It's based on safety buffers growing without your having to think about them constantly.
Check your fixed costs before you save
Before you even start saving, it's worth looking at your fixed costs. Many people in Switzerland pay more in health insurance premiums than necessary, even though they'd be entitled to a subsidy. I experienced this myself and described in the article on applying for a premium subsidy how much you can free up each month that way.
Building financial security with a fluctuating income
Not everyone has a fixed monthly salary. If you work hourly or part-time with fluctuating shifts, you know the problem: sometimes more is left over, sometimes almost nothing. In such months, a percentage instead of a fixed savings amount helps.
I recommend 5 percent of every paycheck, regardless of the amount. On $3,000 that's $150, on $4,000 it's $200. That way the reserve always grows proportionally, no matter how irregular your income is.
If you're also paying down debt, you should do both in parallel, not one after the other. I show how to do that with a clear method in my article on the 50/30/20 rule, which solves exactly this balancing act between paying off debt and building reserves.
How do I build a financial cushion when the budget is really tight?
If even $50 a month seems like too much, it doesn't start with saving, but with spending habits. Back then I wrote down every expense over $20 for three months and was surprised myself how much went to eating out alone.
Often it's enough to question one or two spending habits without completely overhauling your life. In my post on cutting expenses I go into more detail about which items are easiest to adjust without it feeling like sacrifice.
Building a financial cushion doesn't mean giving up everything. It means setting priorities so that the money cushion grows while everyday life stays worth living.
Frequently asked questions about building a financial cushion
How much money should I have as a financial cushion?
As a rule of thumb, three to six months of take-home pay, depending on job security and family situation. If you live alone and your job isn't secure, you should plan toward the upper end of that range.
How fast can I build a financial cushion?
With an automatic transfer of $100 a month, you'll reach a good $1,200 after about 12 months. The pace depends heavily on your starting amount and your fixed costs.
Where should I keep my reserve?
A separate savings account at your bank is perfectly sufficient; the only important thing is that it's kept apart from your everyday account. The return plays a minor role here; availability comes first.
What doesn't count as a financial cushion?
Money in stocks, funds or cryptocurrencies doesn't count, because the value can fluctuate. A reserve must be available at any time without risk of loss.
Is automatic saving really worth more than manual saving?
Yes, because the decision is made once and no longer depends on willpower afterward. That reduces the likelihood of saving falling through in stressful months.
Conclusion: The first step counts more than the perfect plan
Building a financial cushion sounds like a big project, but in the end it's a series of small, repeated decisions. The $50 automatic transfer, the reviewed health insurance premium, the canceled subscription trap, all of it adds up over months to real protection.
Start today with a single step, for example with a separate savings account and a small automatic transfer. You don't have to change everything at once, you just have to begin.